Hello, this is Bota Labo.
CoreWeave (ticker: CRWV), a leading AI infrastructure-focused cloud provider (neocloud), has reported its third-quarter results.
The key question was not revenue, but how the company would address its financial structure, in which interest expense was three times operating income. The bottom line: both revenue and adjusted operating income exceeded company guidance, while interest expense came in below even the low end of guidance. Full-year guidance was also raised. The stock rose about 2.5% in after-hours trading, an initially positive reaction.
Q3 Results: Key Figures
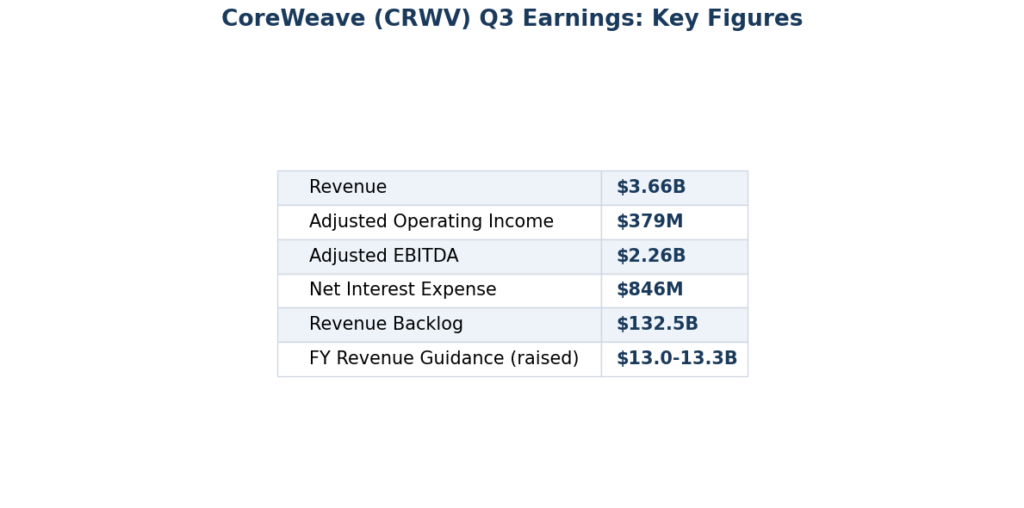
- Revenue: $3.661 billion (approximately 2.7 times the $1.365 billion reported in the same quarter last year), above market expectations of approximately $3.54 billion–$3.56 billion
- GAAP Operating Income: $207 million (6% margin)
- Adjusted Operating Income: $379 million (10% margin). Company guidance was $200 million–$260 million, making this a substantial beat
- Net Interest Expense: $846 million, below even the low end of the guidance range of $860 million–$940 million
- GAAP Net Loss: $709 million / Diluted EPS: -$1.27 (a smaller loss than the market estimate of -$1.46)
- Adjusted EBITDA: $2.256 billion (62% margin)
- Backlog: Approximately $132.5 billion
- Capital Expenditures (Q3 actual): $9.441 billion
- Power in Operation: More than 1.7 GW (over 200 MW added during the quarter). The year-end target of more than 1.85 GW remains unchanged. Contracted power exceeds 4.6 GW
Full-Year Guidance Raised
- Full-Year Revenue: $13.0 billion–$13.3 billion (previously $12.4 billion–$13.2 billion)
- Full-Year Adjusted Operating Income: $1.275 billion–$1.375 billion
- Full-Year Capital Expenditures: $37.0 billion–$39.0 billion (the lower end was raised from the previous range of $35.0 billion–$39.0 billion, as deployment and delivery to customers were brought forward)
- Exit ARR at Year-End (Annualized Revenue): Raised to $20.0 billion–$21.0 billion
- Q4 Net Interest Expense Guidance: $1.05 billion–$1.15 billion
This is where investors should pay attention. Q4 interest expense is expected to increase further from $846 million in Q3, and the structure in which interest expense far exceeds operating income has not yet been resolved.
Why the Stock Fell Approximately 49% in One Month Before Earnings
- Political Risk in Texas: Approximately 40% of the company’s new data center capacity is concentrated in Texas. Gina Hinojosa, who won the gubernatorial election held on November 4, has pledged a moratorium on new data center construction.
- A Yellow Card from the Bond Market: The company’s bonds maturing in 2031 and 2032 fell to 79–80 cents on the dollar, with yields around 16%. CDS spreads also exceeded 1,100 bps.
- Sales by the Founder and Major Shareholders: Following the expiration of the lockup period, the three co-founders collectively monetized more than $2 billion through planned sales, and Magnetar, formerly the largest shareholder, also significantly reduced its holdings.
- Concerns Across the Industry: On October 14, Gartner issued a forecast stating that more than 80% of neocloud providers would abandon independent operations by 2030.
Checking the Key Questions Against the Results
- Interest Expense vs. Operating Income: Interest expense of $846 million came in below the lower end of guidance, while adjusted operating income of $379 million substantially exceeded the upper end of guidance. However, the Q4 interest expense outlook of $1.05 billion–$1.15 billion will be the next major headwind.
- Power in Operation: Exceeded 1.7 GW, with the year-end target of more than 1.85 GW maintained.
- Backlog: Increased to approximately $132.5 billion.
- Financing: Raising the lower end of full-year capital expenditure guidance signals the company’s intention to accelerate investment. However, as funding requirements continue to grow, dilution and interest costs will remain important factors to monitor.
Who Are the Customers?
The main revenue drivers are Microsoft, OpenAI (with cumulative contracts worth approximately $22.4 billion), and Meta (approximately $14.2 billion).
Customer and geographic diversification is also progressing, with partnerships including autonomous driving company Wayve, announced on November 9, and India’s Adani Group.
Conclusion
CoreWeave’s Q3 results demonstrated that demand is holding up strongly in a business where the central dynamic remains: AI demand is real, but interest costs are the enemy.
Revenue, operating income, backlog, and full-year guidance were all positive developments. On the other hand, the financial burden remains unchanged, with Q4 interest expense expected to rise into the $1 billion range.
The next key questions are whether Q4 interest expense stays within the upper guidance limit of $1.15 billion, whether the new Texas administration actually moves forward with a moratorium, and whether accelerated capital investment translates directly into the fulfillment of the company’s backlog.
Source: CoreWeave, “CoreWeave Reports Strong Third Quarter 2026 Results” (November 10, 2026, investor relations release)
Disclaimer
This article is for informational purposes only and does not constitute a recommendation to buy or sell any particular stock. All investment decisions are the sole responsibility of the individual investor. Figures reflect the information available at the time of publication.
Leave a Reply